



How much does product liability insurance cost?
Product liability insurance helps pay for lawsuits related to defective products. It's typically included in general liability insurance, which costs an average of $45 per month for TechInsurance's customers. Your coverage limits, industry risks, and claims history affect the exact cost of this policy, among other factors.
What do small businesses pay for product liability insurance?
If you want to buy product liability insurance, the easiest way is to buy a general liability insurance policy, which usually includes this coverage. Together, the policies cover legal costs from bodily injuries, property damage, and wrongful death caused by your business—or its products.
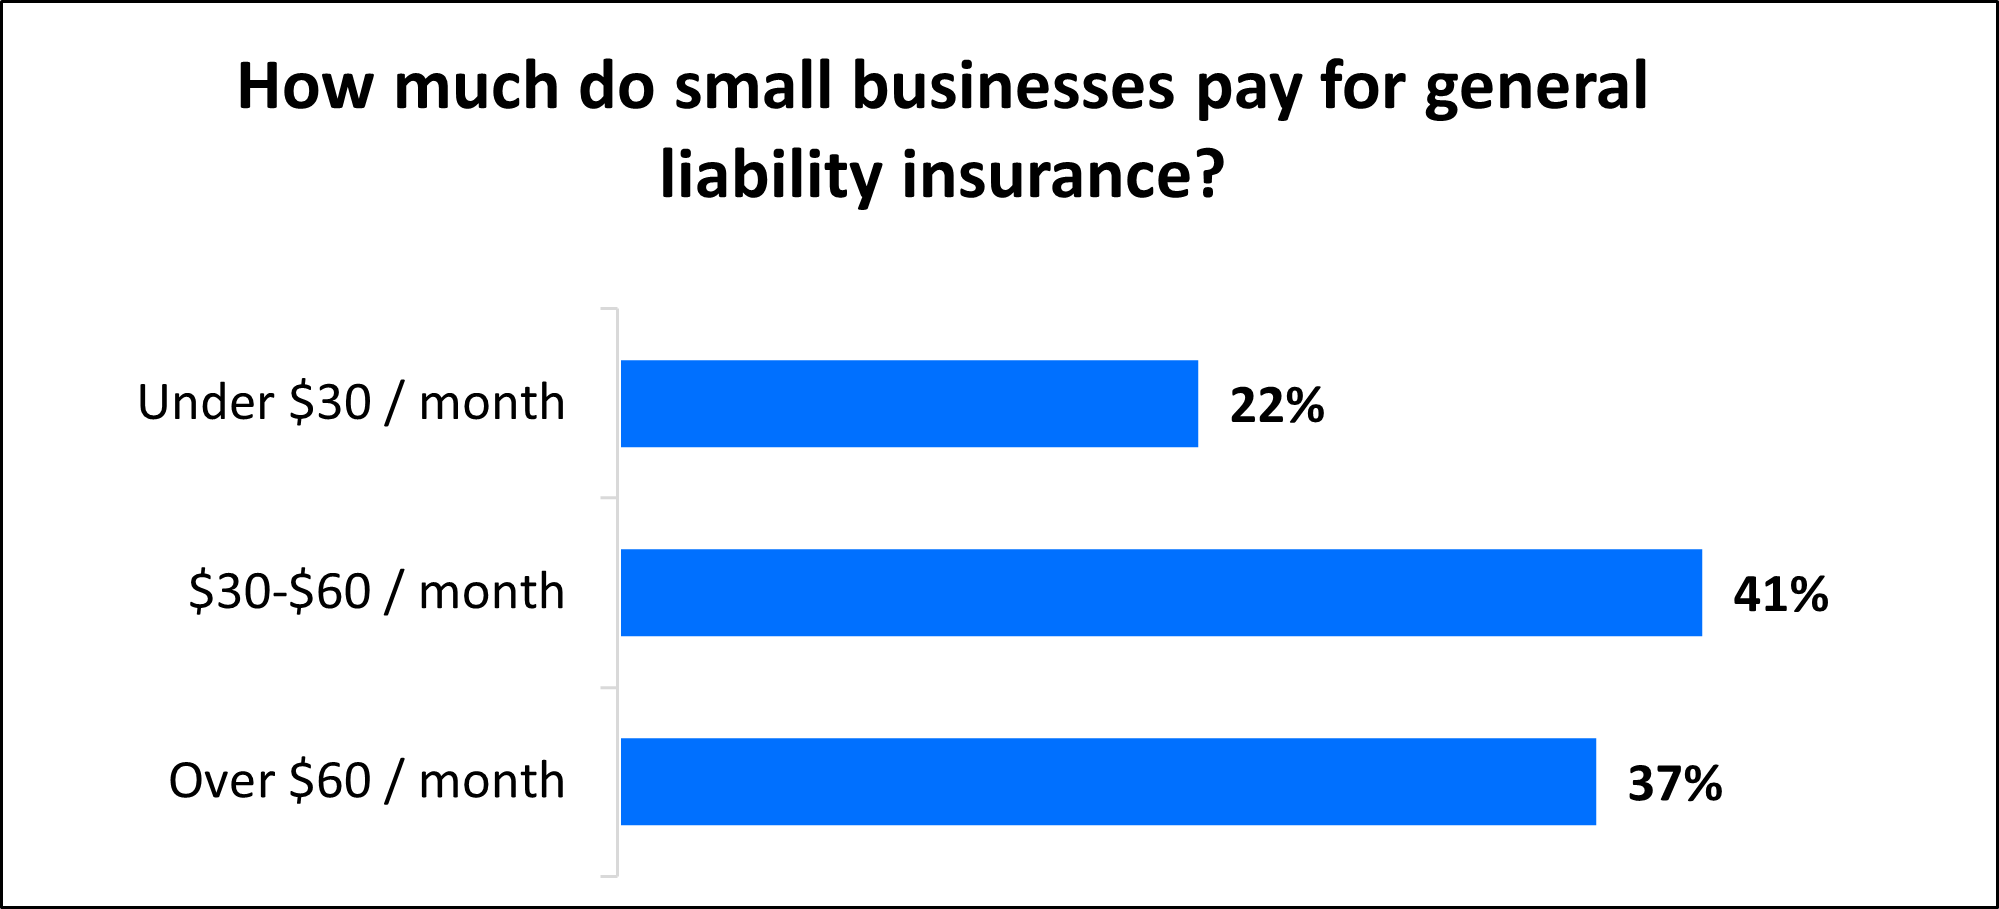
The average cost of general liability insurance is $45 per month, or $538 annually. Most small businesses (63%) pay $60 per month or less for their policies.
Depending on your industry, you may see it referred to as:
- Product liability insurance for businesses such as retailers, manufacturers, and wholesalers
- Products-completed operations coverage for construction and installation businesses
Our figures are sourced from the average cost of business insurance policies purchased by TechInsurance customers from leading insurance providers. The median better reflects what you're likely to pay because it excludes outlier high and low premiums.
Common product liability insurance premiums for TechInsurance customers
TechInsurance small business customers pay an average of $45 per month for general liability insurance, while 22% pay less than $30. Additionally, 41% pay between $30 and $60 per month.
Costs vary for small businesses depending on their risks and their coverages.
General liability insurance costs vary based on factors including your industry risks, business size, and the amount of insurance coverage you choose to carry.
Key factors that affect product liability insurance costs
Here are the top factors that insurance companies consider when calculating your product liability insurance costs:
Additional factors that affect cost:
- Business size
- Type of products you distribute or sell
- Business revenue
- Value of your property
Policy limits and deductible
The amount of coverage you buy, which is reflected in your policy limits, is the most important factor when determining your premium. Product liability insurance has two limits:
- The per-occurrence limit is the maximum amount your insurance company will pay for claims from a single incident.
- The aggregate limit is the most the insurer will pay for claims during the policy period, which is typically one year.
Most small business owners (85%) choose a general liability policy with a $1 million per-occurrence limit and a $2 million aggregate limit.
Businesses that could face expensive product liability lawsuits should opt for higher limits to avoid paying costly legal fees out of pocket. Higher-limit policies cost more, but they cover more expensive claims.
When buying a policy, make sure the deductible is an amount you can easily afford, since your insurance won’t cover your liability claim if you can't pay your deductible. On average, TechInsurance customers choose a general liability insurance deductible between $500 and $1,000.
Location
Business location plays a major role in the premium that you pay. For example, a small business in an area with more foot traffic may pay a higher premium because it faces a higher risk of customer accidents.
Premiums also vary slightly by state. Small business owners in Illinois, for example, pay an average of $40 per month for general liability insurance, while businesses in Montana average $58 per month.
Below are some average product liability costs across different states for TechInsurance customers.
Product liability insurance is recommended for small businesses that manufacture or sell products, but you may need other types of business insurance to be fully covered against common risks.
State laws often legally require small business owners to carry workers' compensation insurance to cover medical costs from work-related employee injuries, as well as commercial auto insurance if they have business-owned vehicles.
Which small business insurance policies does your state require?
Claims history
Position in the supply chain
Industry risks
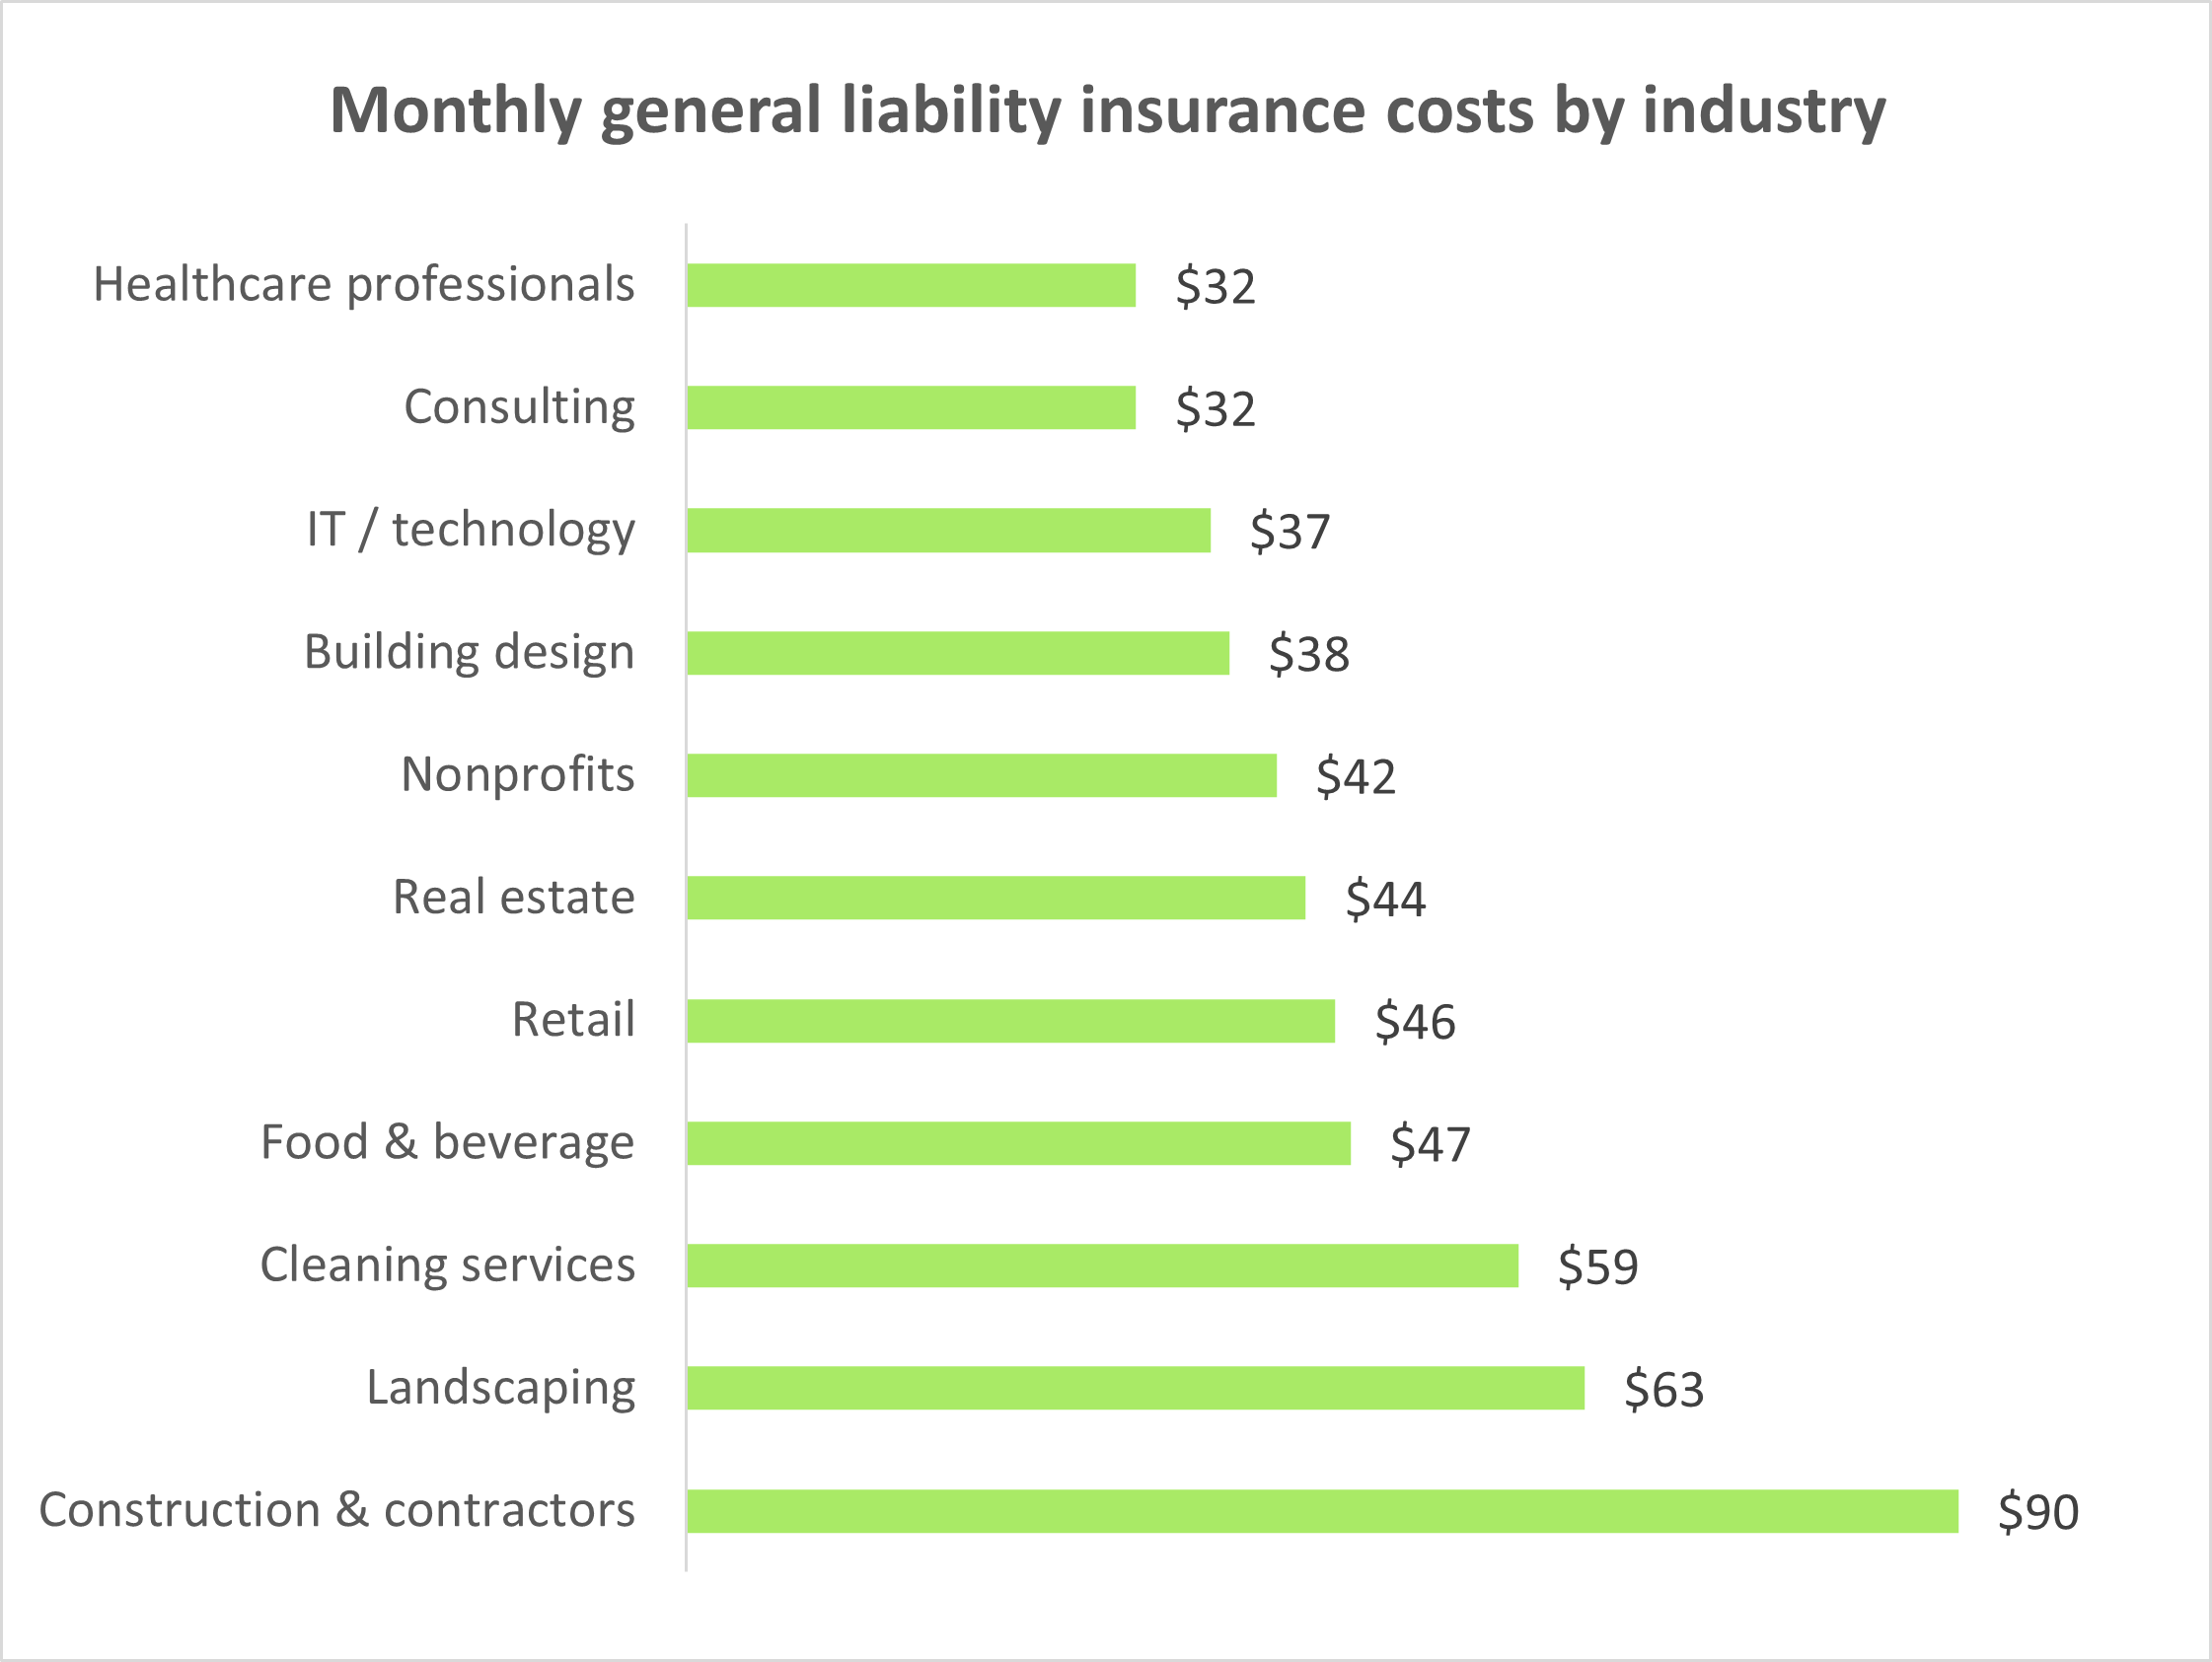
Your industry is a primary factor that determines how much your general liability insurance policy costs. Companies in low-risk industries should expect to pay less for general liability, while industries that carry a higher risk of third-party bodily injuries and property damage will pay more.
For instance, construction businesses pay $90 per month for coverage on average, while e-commerce retailers, on average, pay closer to $46 per month.
Other factors can also affect your premiums, such as annual revenue, employee count, and claims history.


Additional factors that affect product liability insurance costs
Insurance companies will also consider the following factors when determining your premium:
- Business revenue: Generally, higher-revenue businesses have more serious accident and claims rates, making them more expensive to insure.
- Types of products: Businesses that handle higher-risk products, such as those associated with frequent product recalls or high medical or legal defense costs, are more expensive to insure.
- Business size: Larger businesses are often considered higher risk and may pay more because they tend to sell more products, have higher sales volume, and face greater potential claim exposure.
- Value of your business property: The higher your business property value, the more you'll likely pay for insurance because there is more property to protect and replace.
How can you save money on product liability coverage?
General liability insurance is already one of the most affordable policies, but you can still lower your premium.
First, shop around. Insurance companies sell the same types of coverage at different rates. With TechInsurance, you can fill out an online application to easily compare product liability insurance quotes from the nation's leading carriers.
Here are a few other ways to save money on product liability insurance:
- Buy a business owner’s policy (BOP). Small, low-risk businesses may be eligible for a business owner’s policy. A BOP bundles general liability coverage with commercial property insurance at a discount, and typically includes product liability insurance.
- Pay the annual premium. Insurance companies let you pay your premium in monthly or annual installments. Paying the full annual amount will cost less in the long run.
- Reduce your risks. Avoiding product liability claims helps keep your premium low.
Risk management strategies
You can reduce your risk of claims to prevent financial losses and higher premiums.
Because product liability insurance covers potential incidents related to your products and completed services, you might consider:
- Holding employee training on the installation and maintenance of appliances or other items
- Working with trusted partners in your product supply chain
- Testing any products sold at your shop to detect product defects
- Enacting strict quality control to avoid manufacturing defects
- Avoiding products that could cause customer and employee injuries, which could result in high medical costs
- Implementing product labeling to prevent personal injury (such as allergic reactions) and wrongful deaths
Liability claims can be a threat to your business. If you’re accused of injuring someone, damaging property, or causing other harm it could easily turn into a costly lawsuit. That’s why it's important to have the right insurance protection in place to cover a range of potential liability risks.

Am I able to separately purchase product liability insurance coverage?
Most product liability policyholders carry coverage through a standard endorsement to their general liability policy; some insurers may write a standalone product liability policy. This is uncommon.
If you prefer this option, your product liability risks will determine the policy cost. To set the premium, insurers generally consider your company's liability exposure and the potential risk of legal action and costs related to defective products, design defects, product malfunctions, and other product liability issues.
How do you buy insurance with TechInsurance?
TechInsurance is a trusted insurance expert for small businesses, from contractors to consultants, with extensive knowledge of the IT sector. We help business owners compare quotes from top-rated providers, buy policies, and manage coverage online.
By completing TechInsurance's easy online application today, you can compare free quotes for general liability insurance and other policies from top-rated U.S. carriers.
Our licensed agents are available to help answer any questions you may have.
Once you find the right policies for your small business, you can begin coverage in less than 24 hours and get a certificate of insurance for your small business.
Verified general liability insurance reviews
Hear from customers like you who purchased general liability coverage.
Learn more about other business insurance costs
Insurance premiums vary based on the policies a business buys. View our small business insurance cost overview or find out how much you can expect to pay for common types of business insurance.