

How much does directors and officers insurance (D&O) cost?
The average premium for directors and officers insurance is $133 per month. Your coverage limits, industry risk, financial strength, and the size of your business affect the exact cost of this policy, among other factors.
What is the average cost of directors and officers insurance?
Regardless of insurance policy limits, the average cost of directors and officers insurance for a small business is $133 per month. TechInsurance customers can pay between $525 and $12,000 per year, depending on their unique risks.
These estimates were derived from an analysis of the median cost of thousands of insurance policies purchased by TechInsurance's small business customers from leading business insurance companies.
The median cost offers a more accurate estimate of what your business is likely to pay than the average cost of business insurance because it excludes outlier high and low premiums.
Common directors and officers insurance premiums for TechInsurance customers
TechInsurance customers pay an average of $133 monthly for directors and officers liability insurance. 38% of small business customers pay less than $100 per month for their policies, while another 34% pay between $100 and $300 per month.
Most small business owners pay between $525 and $12,000 or more per year, depending on several factors, including their risk and the coverage they choose.
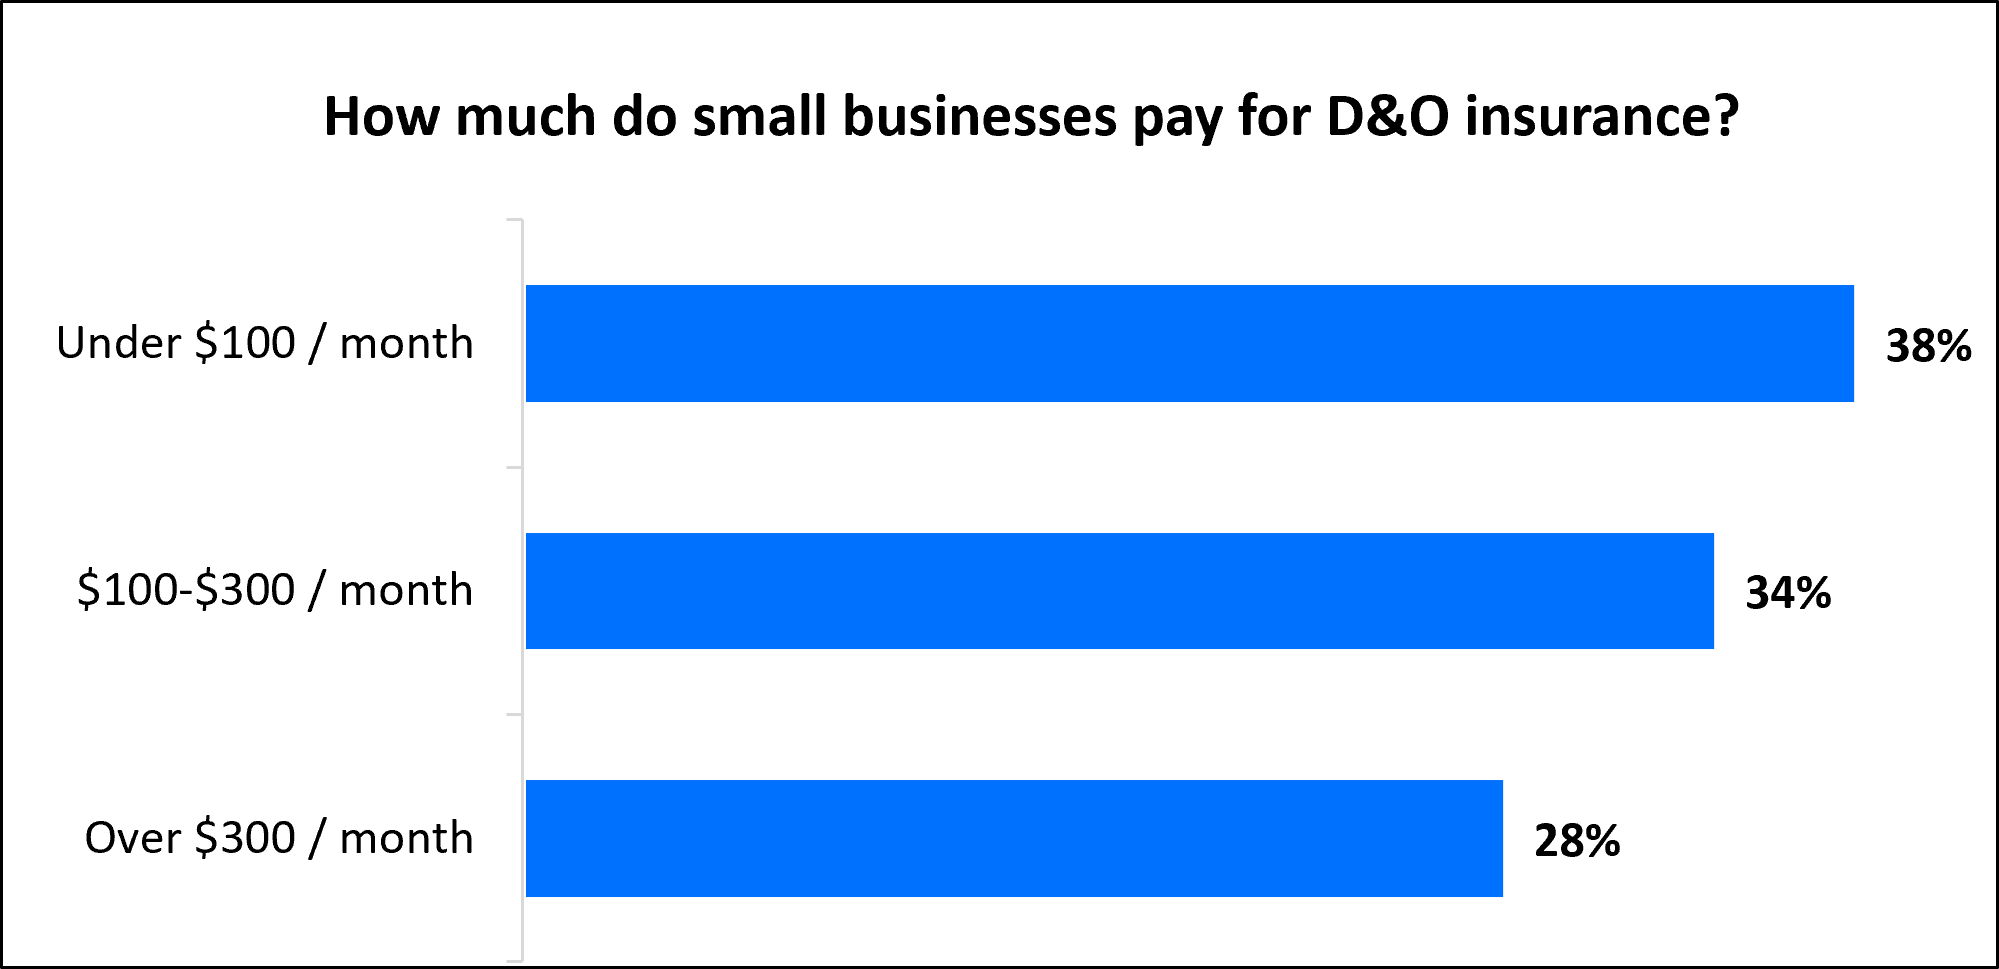
Key factors that affect directors and officers insurance costs
Your insurance provider will look at the following factors when calculating your D&O insurance costs:
Policy limits and deductible
Directors and officers insurance, a type of management liability insurance, is designed to indemnify board members and officers if they are sued for a decision they made on behalf of your company, such as a wrongful termination. This includes defense costs and other legal expenses.
The limits on directors and officers policies vary significantly. Each policy has a per-occurrence limit and an aggregate limit:
- Per-occurrence limit: While the policy is active, the insurer will pay up to this amount to cover claims from a single incident.
- Aggregate limit: During the policy period (usually one year), the insurer will pay up to this amount to cover all claims.
Policies with lower limits will cost less. You can also save money by paying a higher deductible. However, high deductible options may cost more in the long run.
The average policy deductible for a D&O policy is $2,500.
You should consider your unique business needs when selecting the right amount of coverage. Chat with a licensed insurance agent if you're unsure about what D&O limits are right for your small business or startup.
Industry risks
Your industry can significantly affect your premium costs.
Some industries rely heavily on the expertise of their directors and officers. For example, technology businesses and financial services firms often defer to their boards of directors to avoid costly mistakes, and many insurance providers consider them to be high-risk industries.
As a result, technology businesses typically pay $428 per month for this coverage, because these industries often face lawsuits over board-level decisions that can significantly affect the company's financial and legal health.
Professional services businesses pay a moderate average of $144 per month because while their directors often make critical regulatory compliance decisions that carry real risk, it is not to the same extent as other industries with significant capital investments.
Retailers, on the other hand, pay an average of only $73 per month for D&O coverage because their directors and officers tend to prioritize managing inventory and staffing over high-stakes decisions. This generally means fewer lawsuits tied to directors' actions.


Size of your board of directors
The number of directors and officers your business has can influence your D&O insurance premium.
Generally speaking, the larger your board composition, the greater your chance of a securities claim arising from disputes, poor management, regulatory investigations, or wrongful actions.
Because of the risks, your insurance provider may view more board members as a higher exposure and adjust premiums accordingly. Smaller boards of directors typically pose a lower risk of a D&O claim, which can help keep insurance costs lower.
Number of employees
How many employees you hire can also affect your D&O insurance premium. A larger workforce means a greater potential for disputes, mismanagement lawsuits, or employment-related claims.
Employees can potentially bring claims against your board of directors for workplace issues such as wrongful termination, discrimination, or noncompliance with company policies.
Because of the additional risk posed by more employees, insurance carriers may raise premiums for small businesses with larger staff than for those with fewer employees.
Claims history
Annual income
Your annual business revenue is a major factor in determining D&O liability coverage premiums. Higher business revenue can indicate a larger, more complicated business with greater visibility, more stakeholders, and typically more directors on the board.
A larger board of directors can lead to increased legal fees for defending and settling claims, which tend to rise with both company size and board size. Insurance providers generally charge higher premiums to businesses with higher earnings due to the increased risk.
Smaller businesses with fewer directors and lower revenue generally present less exposure and may benefit from more affordable coverage.
Business location
Your state can impact the D&O insurance rates you'll pay, as some states have stronger employee protection laws, more active regulators, or higher rates of D&O lawsuits.
Operating in these states can increase the likelihood that your directors and officers could face expensive claims related to workplace disputes or claims of poor practices.
Insurance providers consider regional costs and risks when setting premiums. For example, small businesses based in states with a reputation for frequent litigation may face higher D&O insurance costs than those in areas with fewer claims.
Risk management practices
Clear policies, documented procedures, and proactive measures can help lower your D&O insurance cost.
A nonprofit that offers employee training, enforces anti-harassment policies, and maintains consistent documentation can demonstrate to carriers that the business is actively managing its risks.
Showing that your company takes compliance, governance, and workplace culture seriously can reduce the risk of D&O claims, make your business a safer bet for insurers, and potentially lead to more affordable premiums.
Does your small business need D&O insurance coverage?
D&O insurance is often not required by state law, but it is critically important when you have a board of directors. Some private equity and venture capital firms may require this coverage before investing in a business or startup.
If your business faces a lawsuit, even if it's a frivolous one, you'll have to pay legal defense costs, and if you lose the suit, you could face significant financial losses in a court-ordered judgment or a settlement.
D&O insurance pays for these costs, which could save your business from bankruptcy in the event of a costly lawsuit. It also helps you attract talented directors and officers who will have confidence that their personal assets will be protected in the event of a lawsuit.
Many small businesses pay only a small monthly premium for D&O coverage because the premium is based on their risk profile and industry.
How can you save money on D&O coverage?
Directors and officers liability insurance benefits both private companies and public companies. Regardless of business type, there are steps you can take to keep your costs low.
A few strategies include:
Bundle policies
Some insurance providers allow small businesses to bundle D&O insurance with other types of management liability insurance coverages, such as employment practices liability insurance (EPLI) or fiduciary liability coverage. These packages usually cost less than purchasing each policy separately.
Compare quotes by shopping around
Pay your annual premium up front
When you purchase a policy, you can pay your premium in either monthly or annual installments. The annual premium often costs less than paying month by month.
Manage your business risks
Companies with no previous directors and officers claims on their insurance will have lower premiums. Your business can avoid claims by creating a risk management plan that includes steps like:
- Refining employment practices to improve employee retention
- Educating the board on corporate bylaws to lessen the chances of a wrongful act
- Prioritizing compliance with industry standards to avoid financial losses
- Responding quickly to claims of harassment
- Implementing a standardized decision-making process to improve the quality and consistency of board decisions
- Establishing a formal review process for key decisions
Liability claims can be a threat to your business. If you’re accused of injuring someone, damaging property, or causing other harm it could easily turn into a costly lawsuit. That’s why it's important to have the right insurance protection in place to cover a range of potential liability risks.

How do you buy insurance with TechInsurance?
TechInsurance is a trusted insurance expert for small businesses, including startups and consultants, with extensive knowledge of the IT sector. We help business owners compare quotes from top-rated insurance carriers, buy policies based on your business needs, and manage coverage online.
By completing TechInsurance's easy online application today, you can get free quotes for directors and officers coverage and other types of insurance. Our insurance agents are available to help answer any questions you may have, such as the differences between Side A, Side B, and Side C in a D&O policy.
Once you find the right policies for your small business, you can begin coverage in less than 24 hours and get a certificate of insurance for your small business.
Explore reviews from our customers
Learn more about business insurance costs
Insurance premiums vary based on the policies a business buys. View our small business insurance cost overview or find out the average costs for other common types of business insurance.